ISA Season Flops as UK Retail Investors Shun Falling Stock Market
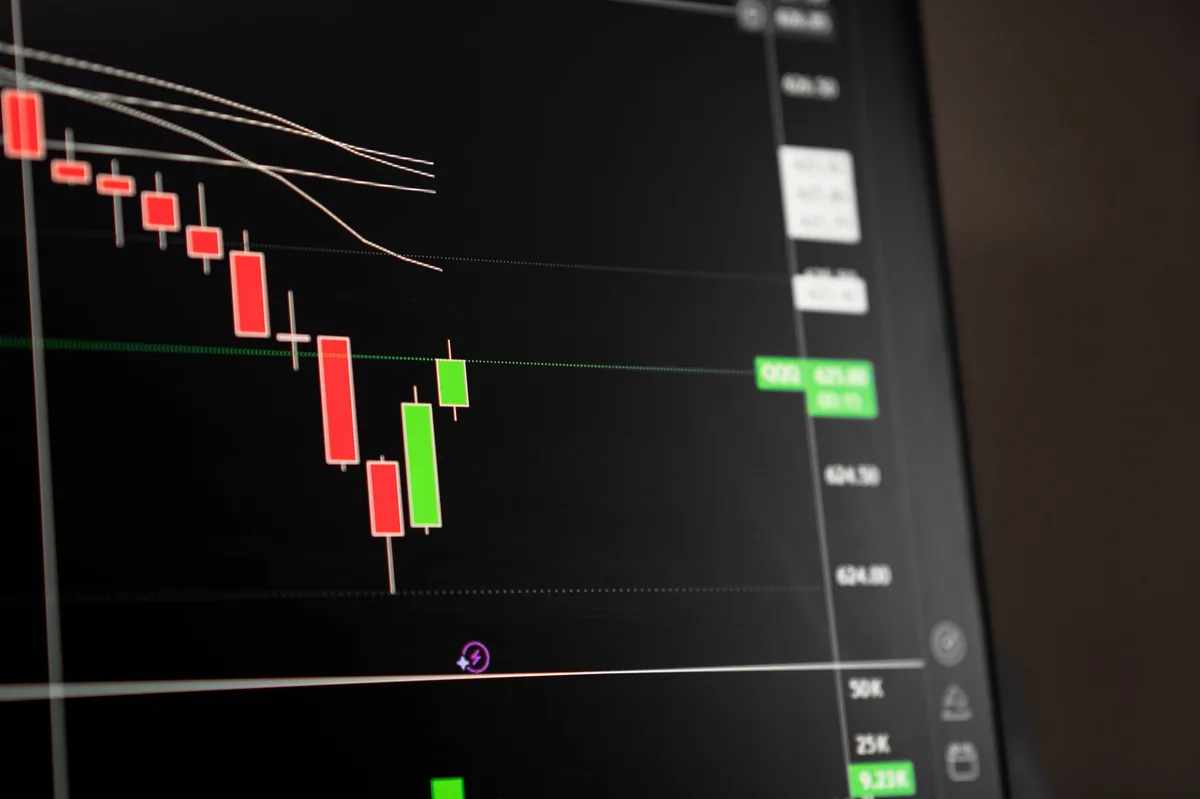
The 2025/26 ISA season saw a sharp decline in Stocks and Shares ISA subscriptions as UK investors favoured cash savings amid market volatility and falling equity prices.
Pexels - Alex Luna · original
In this article
The 2025/26 ISA season, which culminated in the April 5 tax year deadline, recorded one of the weakest performances for Stocks and Shares ISA subscriptions in recent years. While the traditional rush to use annual ISA allowances materialised as expected, retail investors overwhelmingly directed their £20,000 allowances toward cash savings rather than equity markets, marking a significant shift in behaviour driven by falling stock prices and heightened market volatility.
What ISA Season Means for UK Savers
ISA season refers to the concentrated period, typically February through early April, when UK savers scramble to maximise their annual Individual Savings Account allowances before the tax year ends on April 5. The £20,000 annual ISA allowance resets each tax year, and any unused portion cannot be carried forward, creating a powerful incentive to invest or save the full amount (HMRC, 2026).
Savers can choose between Cash ISAs (offering tax-free interest on deposits), Stocks and Shares ISAs (providing tax-free growth and dividend income from investments in equities, bonds and funds), Lifetime ISAs (for first-time buyers and retirement saving), and Innovative Finance ISAs. Historically, ISA season has seen substantial flows into both cash and equity products, with the split reflecting broader economic conditions and investor sentiment.
The 2025/26 Season: A Flight to Cash
The most recent ISA season told a markedly different story. Reports from major platforms and fund managers indicated that Cash ISA subscriptions surged while Stocks and Shares ISA contributions fell well short of previous years’ figures. Several factors converged to create this defensive shift.
First, equity markets entered a prolonged period of volatility and declining valuations. The FTSE 100 experienced notable falls through late 2025 and early 2026, with the FTSE 250 (more representative of UK-focused businesses) suffering steeper losses. International equity markets faced similar headwinds, dampening enthusiasm for diversified global equity funds that typically populate Stocks and Shares ISAs. Retail investors, watching portfolio values erode, became understandably reluctant to commit fresh capital to falling markets.
Second, the Bank of England base rate remained elevated during this period, making cash savings considerably more attractive than they had been in the preceding decade. Fixed-rate Cash ISAs and easy-access Cash ISAs offered returns that, while below inflation, felt safer and more predictable than equity exposure. According to guidance from MoneyHelper, cash products became competitive again after years of near-zero returns, and savers responded accordingly.
Why Investors Held Back from Equities
The reluctance to invest in Stocks and Shares ISAs during a falling market represents a well-documented psychological phenomenon: loss aversion. Investors feel the pain of losses more acutely than the pleasure of equivalent gains, and market downturns trigger a strong impulse to preserve capital rather than deploy it. Even long-term investors, who intellectually understand that market dips can present buying opportunities, often find it emotionally difficult to commit funds when headlines scream pessimism and portfolio statements show red.
Additionally, many retail investors lack the cash reserves or risk tolerance to view market falls as opportunities. For those approaching retirement or holding shorter investment horizons, the prospect of further declines outweighed the theoretical benefits of pound-cost averaging or buying equities at lower valuations. The decision to move ISA allowances into cash, while potentially sacrificing long-term growth, felt rational given immediate uncertainty.
What This Means for Long-Term Investors
From a purely financial perspective, the mass retreat from equity ISAs during the 2025/26 season may prove costly for those investors who allowed emotion to override strategy. Historical market data consistently shows that equity markets recover from downturns, often rewarding those who invested during periods of pessimism. Missing out on tax-free equity exposure within an ISA wrapper during a market trough means forfeiting years of compounded, tax-free growth once markets recover.
Read also: ISA Mid-Year Check in the UK: Using Your Allowance Before the April Deadline
That said, the shift to Cash ISAs was not inherently irrational. For savers building emergency funds, approaching major expenditures, or genuinely unable to tolerate further losses, cash represented the appropriate choice. The ISA structure allows flexibility, as noted in resources from MoneySavingExpert, savers can hold both Cash ISAs and Stocks and Shares ISAs in the same tax year (up to the combined £20,000 limit), enabling a balanced approach.
Lessons from the ISA Season Flop
The 2025/26 experience offers several lessons. First, investor behaviour remains deeply cyclical and emotion-driven, even among those who understand long-term investment principles. Second, the availability of attractive cash rates can fundamentally alter the risk-reward calculus, particularly for conservative savers. Third, the ISA deadline creates a forced decision point that may not align with optimal market timing, though attempting to time markets rarely succeeds over the long run.
Looking ahead, the question for UK investors is whether the pendulum will swing back. If equity markets stabilise and begin recovering, those who stayed on the sidelines may face renewed regret, while those who maintained discipline and invested during the downturn will reap tax-free rewards. Conversely, if volatility persists or markets fall further, the cash-first crowd will feel vindicated, at least temporarily.
Should You Change Your ISA Strategy?
The answer depends entirely on your personal circumstances, time horizon and risk tolerance. Educational resources such as Principles of Finance (OpenStax, 2022) emphasise that investment decisions should be grounded in individual goals and capacity for risk, not in following the crowd or reacting to short-term market movements.
If you have a time horizon of five years or longer, can tolerate short-term volatility, and have adequate emergency savings held separately, Stocks and Shares ISAs remain a powerful vehicle for long-term, tax-free growth. If your circumstances have genuinely changed (job loss, approaching retirement, upcoming major expense), a shift toward cash or a more conservative allocation is perfectly sensible.
What you should not do is make ISA decisions based solely on recent market performance or the behaviour of other investors. The ISA season flop of 2025/26 was a snapshot of collective fear, not necessarily a reflection of sound long-term strategy. As always, consider speaking to an FCA-authorised Independent Financial Adviser to discuss your specific situation and ensure your ISA choices align with your broader financial plan.
Disclaimer: This article provides general educational information about ISA season trends and investment behaviour. It is not personalised financial advice. Nexzoe is not authorised by the Financial Conduct Authority. Tax treatment depends on individual circumstances and may change. ISA rules and allowances are subject to change by HMRC. The value of investments can fall as well as rise, and you may get back less than you invest. Consider consulting an FCA-authorised Independent Financial Adviser for advice tailored to your personal situation.
Sources
- Individual Savings Accounts (accessed )
- Types of Savings (accessed )
- Cash ISAs Guide (accessed )
Related articles
How to Safeguard Your Cash Before ISA Changes Take Effect in the UK
Protect your tax-free savings before UK ISA changes. Step-by-step guide to maximising your allowance, timing transfers, and safeguarding cash.
Why Investing in an ISA in the UK Matters More Than Ever and How to Make the Most of Yours in the New Tax Year
ISAs shield your savings and investments from tax in an era of frozen allowances. Learn how to maximise your £20,000 ISA allowance for the 2026/27 tax year.
ISA Mid-Year Check in the UK: Using Your Allowance Before the April Deadline
Check your ISA contributions mid-tax-year and use your remaining £20,000 allowance before the 5 April deadline. Step-by-step guide for UK savers.
