Finanças
TFSA and RRSP Investors: 2 High-Yield Dividend Stocks to Own for the Next 10 Years in Canada
Two established TSX dividend stocks offering reliable income streams and growth potential for Canadian registered accounts.
Author
RRSP and TFSA specialist helping Canadians optimise registered account contribution room, understand the Home Buyers Plan (HBP) and Lifelong Learning Plan (LLP), and choose between GICs and ETFs.
Two established TSX dividend stocks offering reliable income streams and growth potential for Canadian registered accounts.
A comprehensive guide to capital gains taxation, TFSA and RRSP tax treatment, and key investment tax rules Canadian investors need to navigate in 2026.
The 'Big Short' investor warns most people don't understand their holdings. Here's how Canadian RRSP and TFSA holders can avoid that trap.
As the Bank of Canada adjusts policy rates and inflation expectations shift, Canadian investors holding global funds, ETFs, bonds and thematic strategies face repricing across asset classes.
Most Canadians open an RRSP first, but the TFSA is usually the smarter choice for your first investing account. Here's why the order matters and how to choose the right account for your situation.
As Canadian markets reach new peaks in 2026, investors are reassessing their retirement plans. Learn how current market conditions affect RRSP contributions, TFSA allocations, CPP timing, OAS planning and dividend income strategies.
Turn your CRA tax refund into long-term wealth with these five smart reinvestment strategies for Canadian investors.
Dividend ETFs on the TSX continue attracting Canadian investors seeking reliable income streams. Discover which high-yield funds are dominating portfolios in 2026.
Younger investors in Canada are increasingly turning to covered-call ETFs for income generation amid economic uncertainty. Learn what these products are, why they appeal to millennials and Gen Z investors, and what to consider before adding them to your TFSA or RRSP.
Choosing between a TFSA and an RRSP depends on your current tax bracket, retirement timeline, and whether you need flexible access to your savings.
NEI Investments introduces cost-efficient portfolios combining passive Vanguard equity ETFs with actively managed bonds, offering Canadian investors a middle ground between pure passive and fully active strategies.
A practical guide to budgeting for winter heating costs, reducing energy consumption, and accessing Canadian energy assistance programs.
Learn how Canada Pension Plan and Old Age Security benefits integrate into your retirement income strategy, including timing decisions and tax implications.
Learn how to maximize your Tax-Free Savings Account by investing in stocks, ETFs, and bonds for long-term tax-free growth.
Master the FHSA to save tax-free for your first home. Learn contribution limits, eligibility rules, and how to combine it with the Home Buyers' Plan.
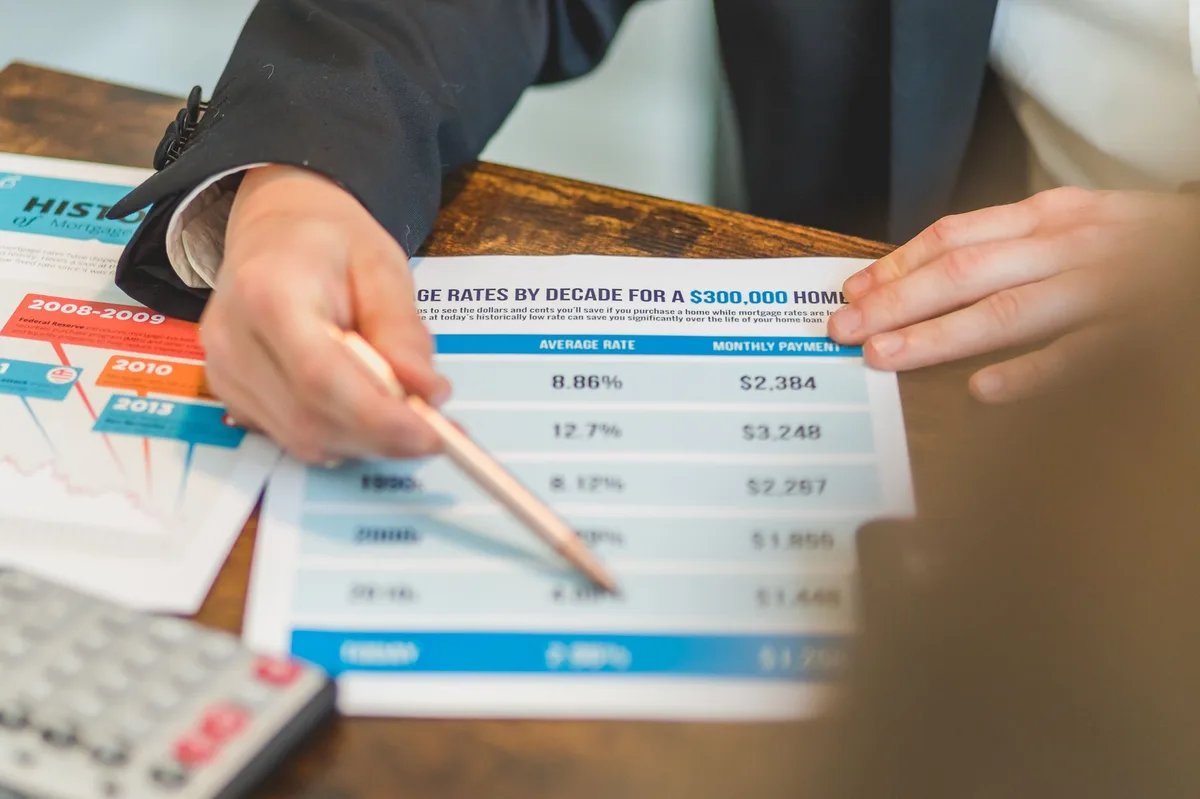
Learn how to decide between accelerating mortgage payments and maximizing RRSP contributions by comparing tax savings, investment returns, and your personal financial timeline.
Compare online CRA My Account with phone, mail, and in-person services to choose the fastest, most convenient way to manage your Canadian taxes and benefits.

Balance transfer credit cards can help Canadians pay down debt faster, but the upfront fee only makes sense when the interest savings exceed the cost.

When you buy a car, the choice between financing and paying cash is not just about whether you have the money. The real question is which option costs less when you account for loan interest, opportunity cost, and what else you could do with your cash.

Index funds charge 0.05-0.25% while active funds charge 1.5-2.5% or more. Understand what you're paying for and whether the premium delivers value for Canadian investors.
Deciding between RRSP and TFSA contributions depends on your income, tax bracket, and financial goals. This guide breaks down the key factors to help you prioritize your registered account contributions.
Compare the First Home Savings Account against RRSP and TFSA strategies to find the best tax-sheltered approach for your first home down payment.

Learn how to make the most of your RRSP contribution room before the CRA's annual deadline and reduce your tax bill.

Choosing between an RRSP and a TFSA depends on your income, tax bracket, and financial goals. Here is how to decide which registered account deserves your contributions first.

The Home Buyers' Plan lets eligible Canadians withdraw up to $35,000 from their RRSP tax-free to purchase or build a qualifying home, with 15 years to repay.
Learn how Guaranteed Investment Certificates work, how they compare to high-interest savings accounts, and when to choose each for your Canadian savings strategy.
Learn how the Basic Personal Amount and non-refundable tax credits reduce your federal and provincial income tax, with a clear explanation of the calculation and a worked example.
Top Canadian savings rates are still competitive, but the best offers depend on whether you need daily access or can lock in a GIC. Here is what to compare this week.
Wealthsimple wants Ottawa to look at investment transfer fees, arguing that Canadians should be able to move accounts without being penalized. Here is what the issue means for RRSP, TFSA, and taxable investors.
A poll suggesting Canadians are leaning toward TFSAs over RRSPs points to a real planning question. The better account depends on income, tax rate, savings goal, and withdrawal timing.
Gold ETFs can give Canadian investors exposure to bullion or gold mining stocks without storing coins or bars. The right choice depends on whether you want direct gold price exposure, Canadian-dollar trading, income, or higher-risk miner exposure.

Mid-year is the perfect time to review your TFSA strategy and make the most of your contribution room before December 31.
Get new articles?
Want notifications about new articles and tools? You can unsubscribe anytime, and we store no personal data about you.